


Credit decisions have gotten much faster over the past decade. Connected bank data and automated underwriting let a lender move from application to answer in minutes. But now borrowers expect that same speed. Yet the money behind that decision still travels at the speed of the channel that sits underneath it.
Take a courier firm that applies for €8,000 on a Friday afternoon to cover a van repair and the fuel it needs to keep its routes running. The lender approves at 16:40. The payment misses the bank’s cut-off, sits over the weekend, and the funds land on Monday morning.
The credit decision took four minutes but the borrower waited for four days. A business that borrows to cover this kind of gap doesn’t have that time to spare.
The Gap Between Approval and Access
A lender rarely controls the last leg of the journey. Once a payment leaves the platform, it passes through a sending bank and a receiving bank, each with its own cut-off times and holiday calendar. Add a first-payment fraud hold or a name check on a new payee, and the timeline stretches again.
Cross-border adds another bump in the road. A platform lending into two countries works around two sets of banking hours, and the borrower feels the slower of them. Throw in a currency conversion and any international fees, and both sides feel even more friction.
Every extra day turns into a support ticket – “Where’s the money?” This is one of the more expensive questions a lending platform has to answer, partly because a person has to answer it, and partly because it comes from borrowers who are already under pressure. Emergency working capital that arrives on Monday was never emergency working capital.
What Happens After the Money Leaves the App
Once funds reach an external bank account, the platform loses sight of them. The borrower spends from their own bank, and the next contact from the lender is usually a repayment reminder. Funding turns into collections with nothing in between.
Clearly, that costs more than goodwill. A second loan to the same borrower gets underwritten on the same thin file as the first, because nothing observable happened in the meantime. A creator who took a €1,200 advance and put it into ad spend looks close to identical on paper to one who used it to plug an overdraft. The platform has very little data to separate them, yet has to price them the same way.
There’s a product cost as well. An app a borrower opens once to apply and once a month to repay has few chances to become anything more than a loan form.
Repayment Runs on Its Own Channel
Money goes out on one channel and comes back on another, usually a direct debit mandate or a card on file. Two channels means two sets of failure modes and two reconciliation jobs, and the second is where the operational cost piles up.
Matching is the slow part. An incoming payment has to be tied to the right loan and split between principal and interest. Partial payments and early settlements each need their own handling.
Then there are the collection failures. On a book of 600 active loans, a monthly failure rate of 3% leaves 18 exceptions to work through by hand, spread across the month one at a time. That work lands on the people who are supposed to be growing the book.
What a Card Changes About the Loop
Issuing a card instead of sending a transfer changes where the money sits at the moment of approval. Funds land on a virtual card inside the platform’s own app, and the borrower can add it to Apple Pay or Google Pay and spend within seconds.
The card also carries the purpose of the loan. Spending controls can hold a facility to the merchant categories it was underwritten against, so an advance approved for parts and fuel behaves that way once it’s live. An advance approved for ad spend can be limited to the platforms it was meant for.
The spending itself becomes visible. The lender sees how fast a balance is drawn down and what it goes to, so the second credit decision has something real behind it. For gig and creator advances, where the applicant often has a thin credit file and several income sources, that signal is worth more than anything on the original application.
Repayment closes on the same structure. Where the platform holds the account and issues the card, disbursement and repayment sit against one balance in one ledger, and matching becomes a lookup. A borrower who settles early moves a balance, and the ledger keeps up on its own.
The Layer Underneath
Wallester White-Label supplies the layer underneath. Wallester manages the regulatory licences, card network connections, and mandatory compliance checks, so a lending platform can issue accounts and cards without building that infrastructure itself.
With Wallester White-Label, you can:
- Launch fully branded physical and virtual Visa card programmes under your own company name
- Integrate card issuing and payment capabilities directly into your lending app via API
- Issue cards instantly with native Apple Pay and Google Pay support
- Apply real-time spending controls and transaction limits tailored to your credit logic
- Offer multi-currency accounts and payment features alongside card issuing
- Rely on Wallester for issuing, payment processing, KYC, KYB, AML, and other ongoing compliance requirements
- Expand across the EEA, UK, and international markets through a single integration
Approval speed is what a credit product competes on, and the wait afterwards is what borrowers remember about it. Moving disbursement onto a card closes the distance between the two, and keeps the money inside one system from the moment it is approved to the moment it comes back.
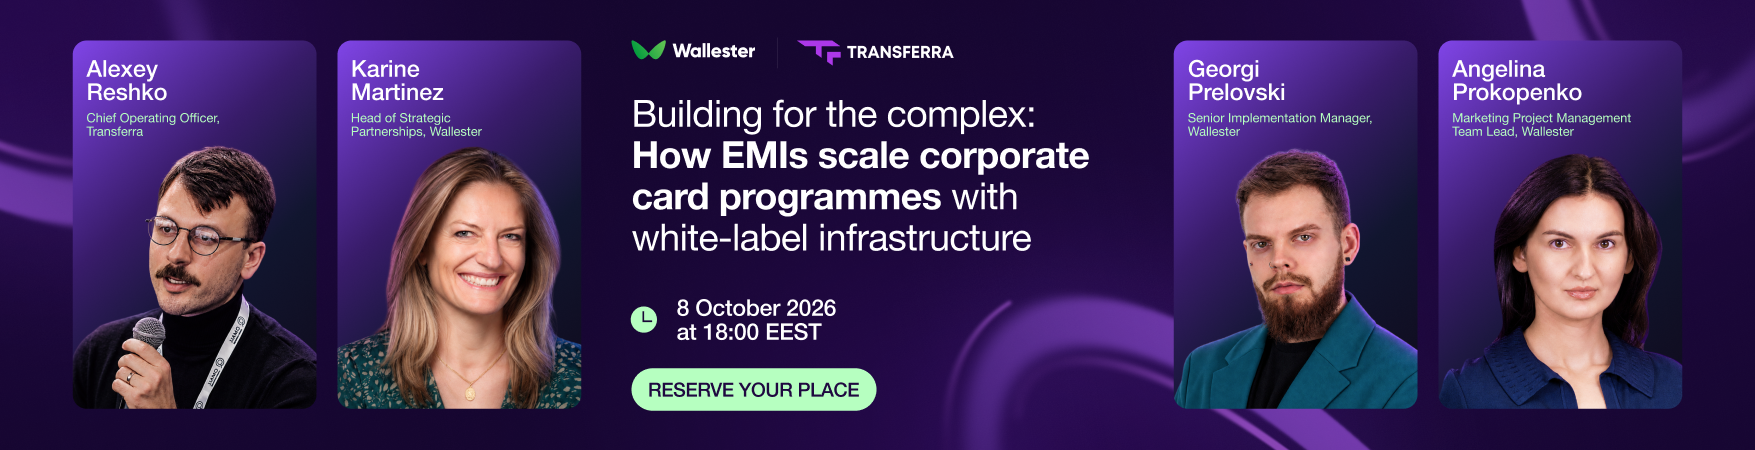
On a related note: Wallester is hosting a live White-Label webinar on 8 October at 6pm EEST, “Building for the Complex: How EMIs Scale Corporate Card Programmes With White-Label Infrastructure.” Over 40 minutes, our team and the COO of FCA-authorised EMI Transferra will cover launching compliant, scalable card programmes without building the infrastructure from scratch, followed by a live Q&A. Places are limited – RESERVE YOURS HERE.
Contact our teamto talk through what a card programme could look like on your platform.

